Compare Offers, Choose a College & Finish Senior Year

An acceptance gives you an option. Your aid offer and the details of the program help you decide whether that option will work. Compare the amount you would actually need to pay alongside what matters to you about learning, support and daily life.

A student and two adults walking together on a college campus.

Compare the costs in your aid offers

Use each college’s actual aid offer together with its cost-of-attendance budget for the same academic year. Check that the budget includes your planned housing, food, books, transportation and personal expenses. An amount labeled “balance” may cover only the college’s bill, leaving other costs out.

Separate the kinds of assistance before comparing totals.

  • Grants and scholarships generally reduce the cost you must cover, provided you meet their conditions.
  • Work-study offers a chance to earn money through an eligible job. You usually need to find a position and work the hours to receive wages. The listed amount is not an upfront payment toward tuition. Federal Student Aid’s work-study guide explains how it works.
  • Loans provide money you borrow and must repay. An offer may list student loans, parent loans or both. Keep the borrower’s name and loan type clear.
Two people compare documents at a table.

Subtract grants and scholarships from the full annual cost first. That gives you the net price before savings, earnings or loans. Federal Student Aid’s offer-comparison guidance explains why the types of aid matter more than a single “total aid” figure.

For your comparison, write down how you would cover the remaining cost. Separate confirmed resources from hoped-for earnings or scholarships. If a line in an offer is unclear, ask the college’s financial-aid office whether it is a grant, a loan or money you must earn.

Look beyond the first year

A college needs to be workable for the time it will take to complete your program. Check whether grants and scholarships renew, how many years they cover and what grades or enrollment level you must maintain. Allow for possible changes in tuition, housing and family circumstances.

If borrowing is part of the plan, estimate the total over the degree. Borrowing $5,000 in each of four years would mean $20,000 borrowed before interest or fees. Actual annual amounts may differ. The Consumer Financial Protection Bureau’s college-cost comparison tool can help estimate debt and monthly payments. Use current loan terms and realistic income and expense estimates.

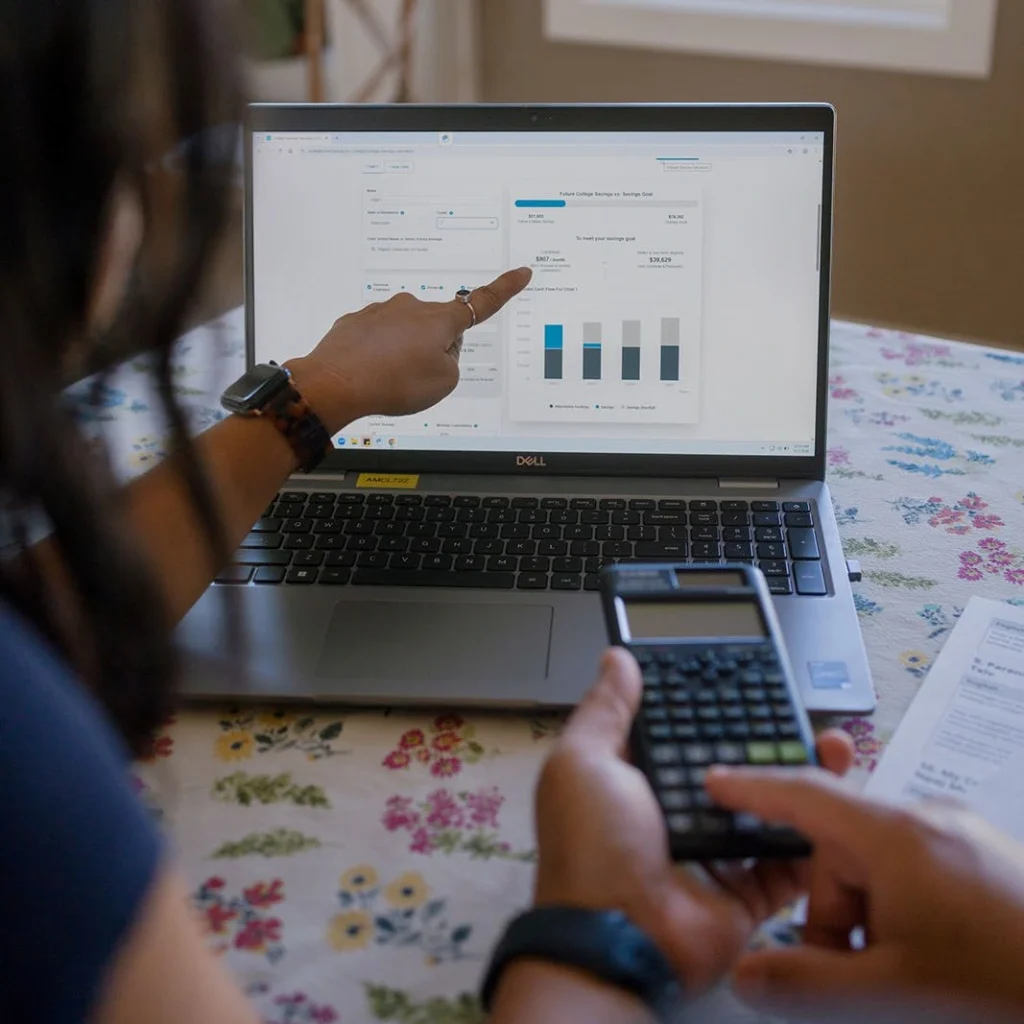
An adult points to a financial chart while using a calculator.

For each loan, check who must repay it, the interest rate, fees and when repayment begins. A federal Parent PLUS loan is borrowed by and repaid by your parent. A private loan may require a cosigner, someone who also agrees to repay the debt. Federal and private loans have different terms and protections. Use the federal student-loan guide for current options and limits before accepting debt.

Bring the cost comparison back to your priorities from Explore Careers, Colleges & Fit. Are you admitted to the program you want? Can you access the academic or disability support you need? Will the location and living arrangement work with your other responsibilities? An admitted-student visit or a focused conversation can resolve a question that would change your choice.

If finances have changed or the aid offer leaves a gap, request a review from the financial-aid office before the decision deadline. Explain the issue and provide any documents it requests. Federal Student Aid’s guidance on aid adjustments explains this option. An adjustment is possible, not guaranteed; keep another affordable option available while waiting.

Make your choice and respond

A student works at a laptop at home.

Use the reply deadline in your admission offer. Many colleges use May 1 for fall first-year enrollment, but ED, rolling admission and other offers can have different timelines. If an aid offer is missing or a review is unfinished, ask whether the college can extend your reply deadline before it passes.

Talk through the tradeoffs with your family, using actual costs and program details. Then accept one college’s offer through its stated process. If you have an ED commitment, follow that agreement. Decline other offers through their portals or the admissions office so the colleges know your decision.

If you choose to remain on a waitlist, follow its instructions while securing a place you can attend instead. A waitlist place is not an offer of admission. If you later accept another college’s offer, withdraw from any waitlists.

After You Choose: Complete Your Enrollment Steps

Your college’s admitted-student checklist and student portal now guide the remaining tasks. Put its summer deadlines in your calendar. Complete the steps that apply to you.

  • Enrollment deposit. Pay by the deadline if required. If the deposit is a barrier, ask admissions about a waiver or deferral before it is due. Check whether it is refundable.
  • Final transcript. Request an official transcript showing graduation and final grades through your high school. Your offer may depend on completing the courses reported in your application. Notify the college if your schedule changes or you encounter a serious academic problem.
  • Financial aid and payment. Respond to your aid offer, complete outstanding document requests and accept only the loan amount you choose to borrow. Complete any required loan agreement and entrance counseling, which explains your borrowing responsibilities. Check when the first bill is due and how it will be paid.
  • Housing and meals. If you will live on campus, complete the housing application, contract and meal-plan choices by their deadlines. Arrange housing separately if you will live off campus.
  • Orientation and course registration. Sign up for required orientation and advising. Complete any placement assessments used to identify an appropriate starting course in subjects such as math or a language.
  • Prior college credit. Send official AP or IB scores and dual-enrollment college transcripts when needed. Review how the college applies them before selecting courses.
  • Student accounts and email. Activate your college accounts and begin checking college email for messages about registration, aid and deadlines.
  • Health and support requirements. Submit immunization or other health records if required, and review any health-insurance requirement. If you need disability accommodations, contact the college’s disability services office before classes begin.

Before the term starts, check the portal for unfinished tasks and confirm your class schedule, housing or commuting plan, and payment arrangements. Share the travel and payment details your family needs to support your move into college.